
Why My Paycheck Always Vanished Before Payday
Most budgeting advice fails because it demands that you log every single penny until you burn out. If you are sick of watching your paycheck disappear by the second week of the month, you do not need more willpower—you just need a realistic three-bucket cash system. Here is the exact, step-by-step split I use to cover my bills, grow my savings, and still spend money on the weekends without an ounce of guilt.
My money just seemed to vanish into thin air, leaving me with a heavy chest and a familiar knot in my stomach. I felt like I was working so hard just to stay exactly in the same place.
I constantly asked myself where all my hard-earned money was going, but I never had a clear answer. That was the moment I realized my random approach to handling money was completely destroying my peace of mind. I needed a system that actually made sense for a normal person like me.
This silent stress of living from one paycheck to the next is something millions of people deal with every single day. You wake up early, fight through traffic, and work long hours just to earn a living. But when the bills roll in, you are left playing a stressful guessing game with your bank account.
The constant worry about unexpected expenses creates a dark cloud over your everyday life. You might find yourself dreading the simple act of opening your mail or checking your email for utility bills.
Even buying groceries starts to feel like a high-stakes math test where one wrong move means your card gets declined. This financial anxiety steals your joy, ruins your sleep, and puts unnecessary pressure on your personal relationships.
We often blame ourselves for this mess, thinking we just lack discipline or willpower. You might try strictly tracking every single penny on a complicated spreadsheet for a few days. But eventually, life gets busy, you miss a few entries, and you abandon the whole tracking system completely out of frustration.
The truth is, you do not lack willpower. You simply lack a realistic system that matches human psychology. When money management feels like a strict diet where you are starving yourself of fun, you are bound to fail.
People need a method that provides clear boundaries but still allows them to breathe and enjoy their lives.
Before we dive into the details, here’s what you need to know:
- The Split: Divide your take-home pay into 50% for core survival needs, 30% for guilt-free lifestyle spending, and 20% for debt payoff and savings.
- No Penny-Tracking: Forget logging every cup of coffee; simply separate your cash into different accounts and spend whatever is in that bucket.
- Automate First: Move your 20% future shield cash to a separate bank the day you get paid so you never get the chance to spend it.
- Stay Flexible: In high-cost-of-living areas, it is completely normal to start at 60/20/20 and work your way back over time.
The Core Logic Behind Stress-Free Money Management
To fix this exhausting cycle, we have to rethink exactly how we view our income the second it hits our bank accounts. Most people practice what I call "hopeful spending," where they pay a few bills, buy what they want, and hope there is something left to save.
This backwards method is exactly why savings accounts stay empty. We need a system that organizes our money before the emotions of the day can take over.
The 50/30/20 method is incredibly effective because it removes the heavy cognitive load of making daily financial decisions. You do not have to create twenty different micro-categories for your spending.
Instead, your entire financial life is sorted into just three simple buckets. This gives your brain the clarity it needs to make smart choices without feeling overwhelmed by complex math.
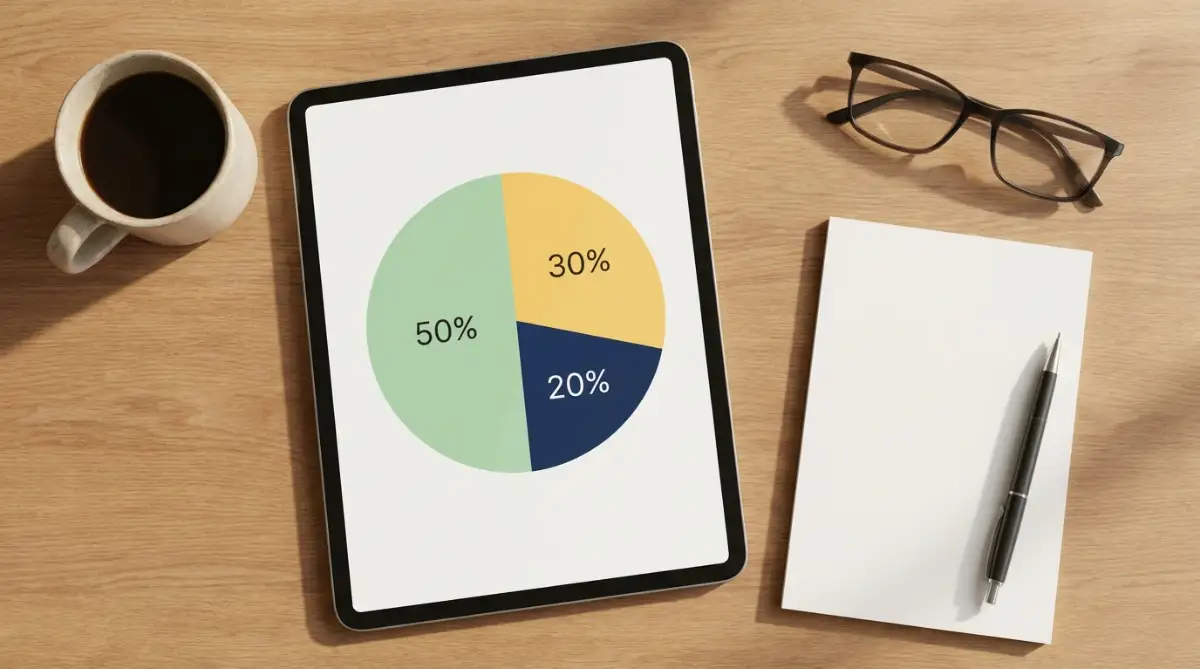
Securing Your Baseline Survival (The 50% Rule)
The very first bucket you need to fill is your absolute necessities, which should take up no more than half of your take-home pay. These are the expenses that keep a roof over your head, food in your stomach, and the lights on in your home.
We are talking about your rent or mortgage, basic utilities, groceries, and essential transportation to get to work.
If you lose your job tomorrow, these are the bills you would still legally and physically have to pay. It is highly important to be brutally honest with yourself when defining what a true necessity is.
A lot of us fall into the trap of upgrading our lifestyle and calling those upgrades "basic needs."
For example, basic groceries to cook at home are a necessity. However, ordering expensive takeout from a fancy restaurant three times a week is not.
Having a reliable internet connection is required for modern life and work. But paying for five different premium streaming services is entirely optional.
When you keep your basic living costs under that halfway mark, you build a powerful financial shock absorber. If emergencies happen or your income drops, you have plenty of breathing room in your budget to adjust.
You will never have to panic about keeping the lights on because your foundation is incredibly solid.
Here is a quick reality check: If your basic needs are taking up 70% or 80% of your income, you are in a danger zone. You will need to either find a way to significantly increase your income or make tough choices to lower your fixed housing or car costs.
Funding Your Happiness Without Guilt (The 30% Rule)
Watch This Quick Breakdown First!
If you are a visual learner, this quick video perfectly breaks down how you can enjoy your money without feeling guilty, giving you the exact confidence you need to master your daily spending.
Now, let us talk about the most exciting part of this entire system, which is your personal lifestyle bucket. You get to dedicate almost a third of your hard-earned money entirely to things that bring you joy and comfort.
This is your money for dining out, buying new clothes, taking weekend trips, or upgrading your gaming console.
The main reason most traditional budgets fail is because they try to completely eliminate fun. If you tell yourself you will never buy another cup of coffee or go to the movies again, you will eventually rebel.
It is exactly like going on a crash diet where you eat nothing but cabbage soup for a week. Eventually, you snap and eat an entire chocolate cake in one sitting.
By legally giving yourself permission to spend 30% of your money on pure wants, you eliminate financial guilt entirely. When you buy that fresh cup of iced coffee, you do not have to feel bad about it.
You know for a fact that your bills are already covered and your future is secure.
I remember when I first started trying to fix my finances, I cut out every single hobby I loved. I lasted exactly two weeks before I got depressed, went to the mall, and completely blew my budget on things I did not even need. My biggest realization was that scheduled fun money is actually the secret glue that keeps a budget together.
Of course, the trick here is actually stopping when the 30% bucket is empty. This requires a bit of mindfulness and tracking.
If you spend all your fun money in the first two weeks of the month, you have to be disciplined enough to stay home and read a book for the remaining two weeks.
Building Your Unshakeable Wealth Shield (The 20% Rule)
The final piece of the puzzle is arguably the most powerful part of this entire framework. One-fifth of everything you earn must be aggressively directed towards securing your financial future.
This bucket is strictly for building an emergency fund, investing for retirement, and destroying any toxic debt you might have.
Paying yourself first is a concept you hear often, but this system actually forces you to do it. Every time you get paid, this money should ideally be moved automatically before you even see it.
If you wait until the end of the month to save whatever is left over, there will never be anything left over. Human nature always finds a way to spend visible money.
Your very first target in this category should always be building a starter emergency fund. Life is incredibly unpredictable, and cars break down, appliances die, and medical emergencies happen.
Having a thick cushion of cash sitting in a high-yield savings account turns major life disasters into minor inconveniences.
Once your emergency cash is secure, this money shifts toward aggressive wealth building. You can start putting it into index funds, retirement accounts, or other stable investments.
Over time, compound interest takes over, and your money starts going to work for you. You eventually reach a point where your money is earning its own money.
If you are carrying high-interest credit card debt, this bucket is your primary weapon to destroy it. High-interest debt is a massive financial emergency that slowly drains your wealth every single day.
You should temporarily throw every spare penny from this category at your credit cards until the balance hits zero.
Making the Math Work in the Real World
Let us look at a highly practical scenario so you can see exactly how this works in real life. Imagine you bring home exactly $3,000 every single month after all your taxes are taken out.
Using this framework, we can easily break down exactly where every dollar should go.
Your baseline survival bucket gets $1,500. This must cover your rent, your groceries, your electricity, and your basic transportation.
Your happiness bucket gets $900. This is a massive amount of money to spend on restaurants, hobbies, entertainment, and shopping without any guilt.
Finally, your wealth shield gets $600. You send this directly to your savings account, your investments, or your credit card debt.
When you look at the numbers this clearly, personal finance suddenly stops being terrifying. It becomes a simple, manageable math equation that anyone can solve.
Here is a quick look at how this split works across different monthly take-home pay levels:
Pro tip: Always base your percentages on the money that actually hits your account, not your gross salary before taxes.
Overcoming the High Cost of Living Obstacle
Now, you might be thinking that these percentages are impossible in today's economy. If you live in a major city, your rent alone might consume 50% of your take-home pay.
This is a very valid concern, and it is exactly why this framework is a guideline, not a strict law.
If your basic needs are creeping up to 60% or 65%, do not panic and throw the whole system away. You simply have to adjust the other buckets to compensate for your current reality.
In this scenario, you might have to reduce your fun money bucket down to 15% or 20% to make the math work safely.
The goal is to eventually work your way back to the ideal percentages. You can do this by negotiating your bills, finding a cheaper place to live, or focusing heavily on increasing your income.
Taking on a side hustle or asking for a raise can quickly bring your percentages back into perfect balance.
What truly matters is that you are actively paying attention to where your money is going. Just the simple act of dividing your income into these three distinct categories will dramatically change your spending behavior.
You will naturally start questioning your purchases and making smarter choices every single day.
You no longer have to be the person staring blankly at a banking app wondering where the money went. You now have a ridiculously simple blueprint to take back control of your paycheck.
Start with your very next paycheck, divide it into three buckets, and watch how quickly your financial stress begins to fade away.
Mastering the Money Game With Pro-Level Hacks
Now that you understand the basic math, it is time to turn this concept into an automatic lifestyle. Knowing the rules is great, but executing them daily is where the real magic happens.
Most people fail at budgeting because they rely entirely on their daily willpower. Willpower is an extremely limited resource that completely drains by the end of a long, stressful workday.
If you have to make a conscious choice every single time you want to save a dollar, you will eventually choose to spend it instead. To make this framework truly stick, you have to completely remove yourself from the decision-making process.
The smartest thing you can do is set up a digital banking architecture that does the heavy lifting for you.
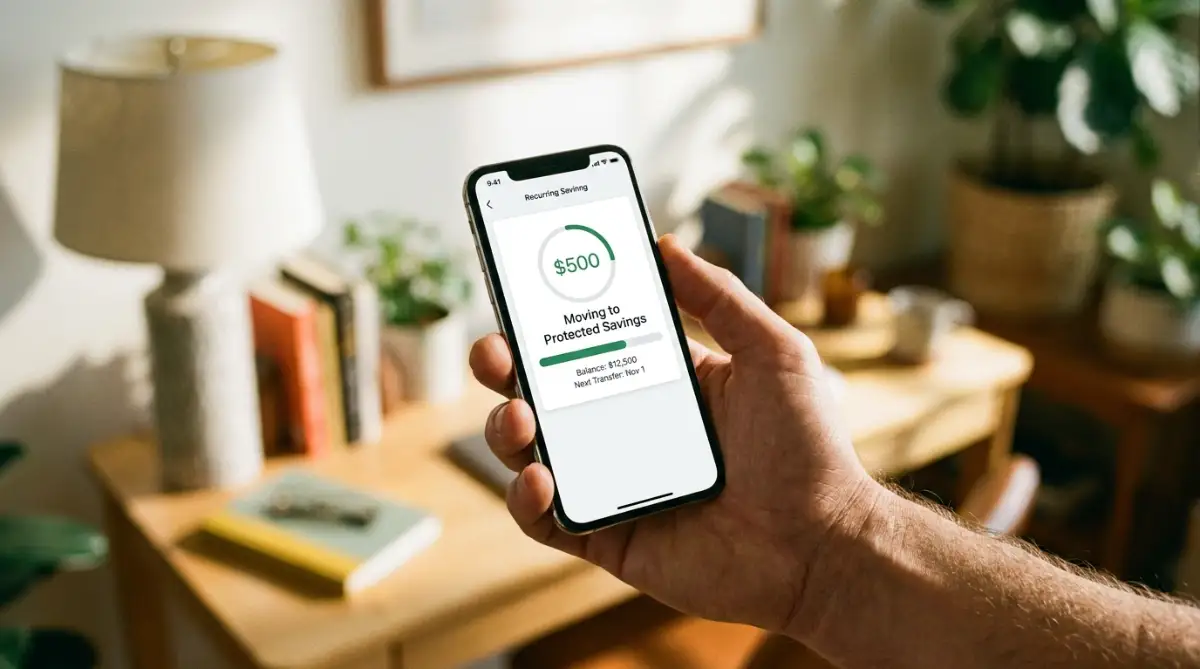
The Two-Bank Architecture Strategy
My absolute favorite trick is using multiple bank accounts to physically separate my cash. When all your money sits in one giant checking account, it creates a false sense of extreme wealth.
You look at that big number on payday and suddenly feel like you can afford a luxury weekend getaway. This optical illusion is exactly why people overspend during the first week of the month.
Instead, I highly recommend opening accounts at two completely different banks. Your main bank will hold your 50% survival money and your 30% happiness money in two separate checking accounts.
Your second bank, preferably an online bank with a high-yield savings option, will hold your 20% wealth shield.
When your paycheck clears, automatically transfer that 20% straight to the hidden bank before you even buy your morning coffee. By completely removing this money from your daily view, you will not be tempted to spend it.
Securing your financial privacy and protection is a lot like securing your digital life. Just like a VPN protects your online privacy on public networks from hidden threats, this separate banking structure shields your savings from your own impulsive spending habits.
Stop Tracking Pennies and Start Tracking Averages
Another major secret is to stop obsessing over every single receipt. Traditional finance gurus will tell you to log every pack of gum you buy into a complicated spreadsheet.
For a normal person managing a busy life, this is completely exhausting and unsustainable. According to behavioral science research from Stanford University regarding habit formation, overly complex routines are almost always abandoned quickly.
Instead of tracking pennies, focus purely on tracking your overall category balances. If your 30% fun account has $400 left for the month, you know you are safe to go out to dinner.
You do not need to mentally calculate the exa